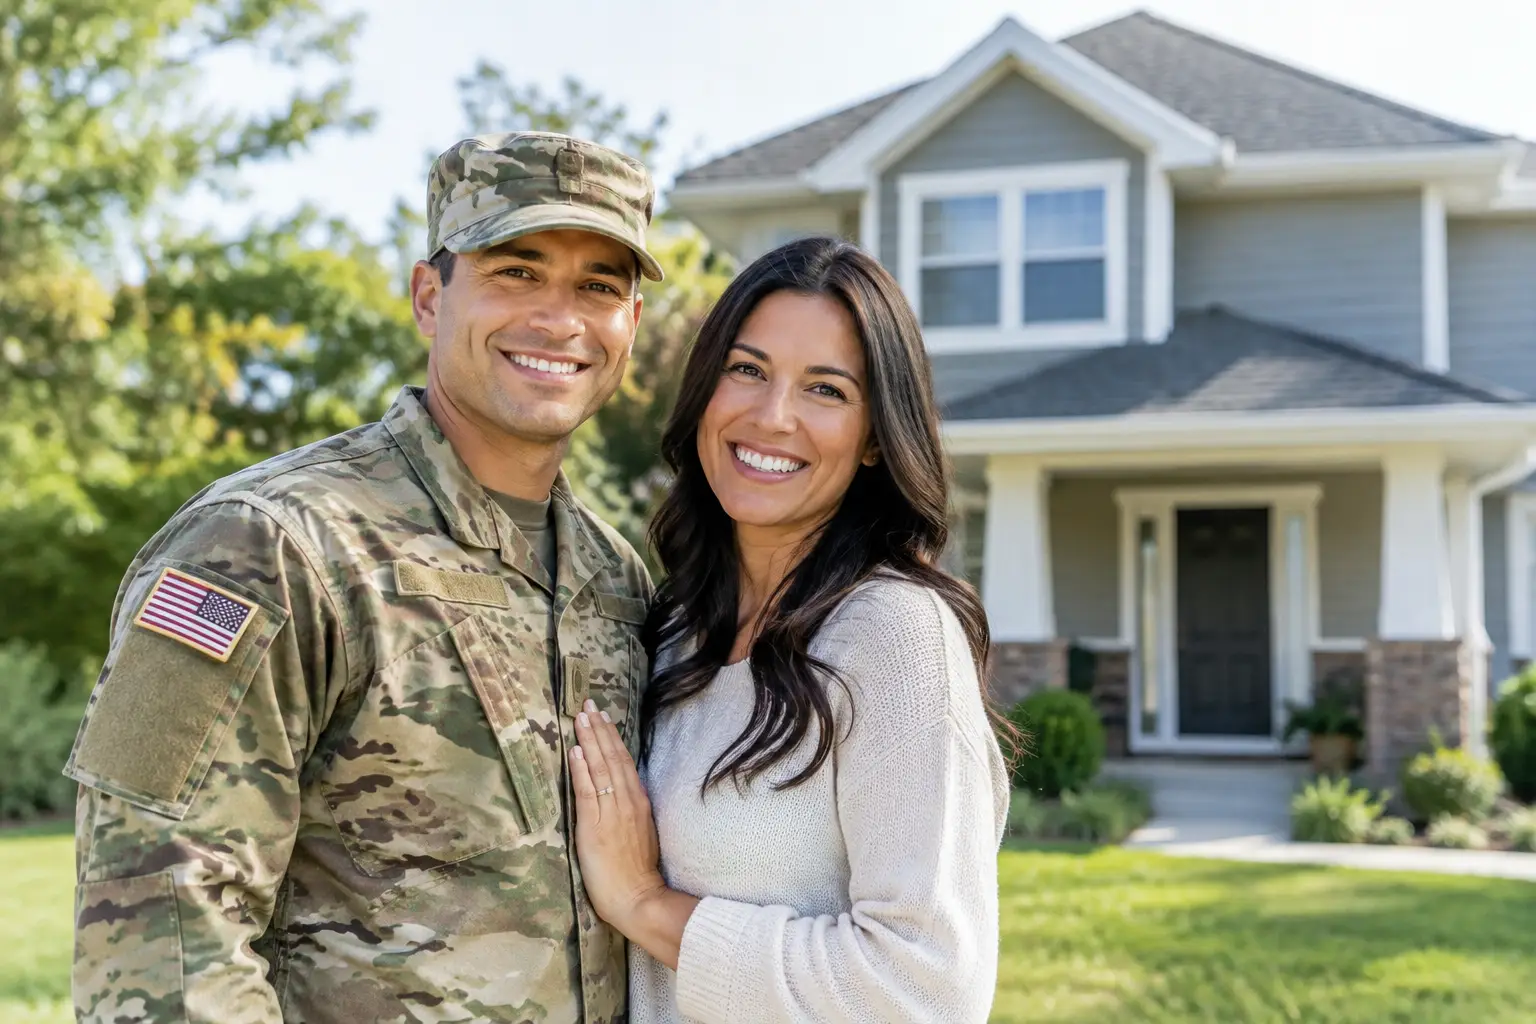
A strong offer is not simply the highest number on the page. In this veteran home purchase case study, a recently separated service member used a VA loan to buy in Bucks County while protecting cash reserves, addressing inspection concerns, and competing against conventional financing. The result was not a rushed win. It was a purchase structured around the buyer’s actual priorities.
The scenario below is a composite based on common issues veteran buyers face in the Pennsylvania and New Jersey markets. Names and certain details have been changed, but the decisions, risks, and negotiation approach reflect the work required to make a VA-financed purchase successful.
The veteran home purchase case study
The buyer, whom we will call Mark, had accepted a civilian job outside Philadelphia after leaving military service. He and his spouse had been renting while deciding whether to settle in Pennsylvania or New Jersey. Their lease was ending, they had one child, and they wanted a home with a reasonable commute, a usable yard, and enough room to stay put for several years.
Their first assumption was that a VA loan would make the process easy because they could purchase with no down payment. That benefit was meaningful, but it did not remove the need for planning. Mark still needed money for earnest money, inspections, appraisal-related costs, moving expenses, and the prepaid items due at closing. A zero-down loan does not mean a zero-cash transaction.
Their lender approved them up to $480,000. Rather than treating that figure as a shopping target, we worked backward from the monthly payment they could comfortably carry while preserving an emergency fund. That shifted their preferred price range closer to $440,000 to $465,000. It gave them room to handle normal ownership expenses after closing instead of stretching every dollar to win a bidding contest.
The first decision: loan readiness before house hunting
Before scheduling a full weekend of showings, Mark connected with a lender experienced in VA financing. The lender confirmed his Certificate of Eligibility, reviewed income from his new position, and explained whether a VA funding fee would apply. Veterans with certain service-connected disability ratings may be exempt from that fee, but buyers should never assume an exemption without confirmation from the lender.
That early work mattered when the right property came up. Sellers and listing agents wanted confidence that Mark could perform. A vague preapproval letter would not be enough in a competitive market. His offer package clearly stated the loan type, the financing timeline, and the fact that underwriting documents had already been reviewed.
VA financing should not be treated as a weakness. It becomes a concern only when the buyer, lender, and agent are not prepared. Clear communication changes that perception.
Finding the right home, not just an available home
Mark’s family found a well-maintained colonial listed at $465,000. It had the location and layout they wanted, but it was not perfect. The HVAC system was nearing the end of its expected service life, an exterior handrail was loose, and there was peeling paint on a detached shed.
Those details required attention for two reasons. First, an inspection could reveal costs that affected Mark’s budget. Second, VA appraisals include minimum property requirements intended to confirm that a home is safe, sound, and sanitary. The VA appraiser is not a substitute for a licensed home inspector, but obvious health and safety issues can create conditions that must be resolved before closing.
Some buyers hear this and decide they should avoid any house with an older system, a repair item, or cosmetic wear. That is not the right lesson. Every home has trade-offs. The job is to determine whether the issues are manageable, priced appropriately, and acceptable within the buyer’s plans. An older HVAC unit that is functioning properly is different from a failed system in the middle of a tight closing timeline.
Building an offer a seller could trust
The sellers had interest from several buyers, including at least one conventional buyer. Mark did not try to win by waiving every protection or offering a number that would leave him financially exposed. Instead, the offer was built to reduce uncertainty for the seller while keeping the important safeguards in place.
He offered the asking price, used a meaningful earnest-money deposit, and accepted the seller’s preferred closing date. His inspection contingency was focused and reasonable, allowing the family to investigate major systems without turning minor cosmetic items into a negotiation battle. The financing and appraisal timelines were realistic, not artificially aggressive.
That distinction is important. Waiving an inspection can appear attractive, but it is not automatically smart, particularly for a first-time buyer using savings carefully. A buyer can be serious, cooperative, and competitive without agreeing to purchase blind. Good representation means explaining the risk before the offer is signed, not after a problem appears.
The seller accepted Mark’s offer because it was clean, credible, and supported by a lender who could communicate. Price got attention, but certainty helped get the contract signed.
Inspection and appraisal: where the deal could have changed
The home inspection confirmed that the HVAC system was operational but aging. It also identified the loose handrail, minor electrical corrections, and the shed paint issue. A separate sewer scope showed a clear line, which gave Mark useful peace of mind on an older property.
The buyer did not ask the seller to renovate the house. He focused on items connected to safety, loan requirements, and near-term financial risk. The seller agreed to repair the handrail and address the peeling paint before appraisal. For the HVAC, the parties negotiated a $4,500 credit toward allowable closing costs rather than demanding replacement of a system that was still working.
That solution fit both sides. The seller avoided a larger, open-ended repair project. Mark kept more cash available after closing, which mattered because he expected to replace the HVAC in the next few years. The lender and title team confirmed how the credit could be structured within VA loan guidelines and Mark’s actual closing costs.
This is where disciplined negotiation matters. A credit is not always the best answer. If a repair is required for safety, appraisal conditions, or insurance, completion before closing may be necessary. If a buyer has little in allowable closing costs, a large credit may not provide the value they expect. The right choice depends on the property, loan terms, and the buyer’s financial position.
The VA appraisal came in at the contract price. Because the listed safety items had been addressed, there were no appraisal conditions that delayed the closing. The transaction moved forward without forcing Mark to bring additional money to the table for an appraisal gap.
What this VA home purchase shows
The outcome was a home purchase that met the family’s needs without draining the reserves they had worked hard to build. Mark used his VA benefit, but he did not rely on the benefit alone. He had a realistic payment target, loan guidance before making offers, a defined inspection strategy, and a negotiation plan based on facts rather than emotion.
Veterans and military families should also remember that VA loans are not identical from lender to lender. Rates, lender fees, communication standards, underwriting capacity, and familiarity with military income can vary. Choosing a lender who understands the program is part of protecting the transaction.
The same is true of property selection. A VA buyer does not need to limit the search to flawless homes, nor should they accept a home with unresolved problems just to avoid losing it. In the greater Philadelphia market and across Pennsylvania and New Jersey, the best purchase is usually the one that balances location, condition, monthly cost, and future flexibility.
A purchase should fit the mission
Buying after service can bring a different kind of pressure: a new job, a new community, changing family needs, and a major financial commitment all at once. The answer is not to move faster. It is to make each decision with clear information and a representative willing to speak plainly about the risks.
A home should support the next chapter of your life, not become the expense that limits it. The right plan gives you the confidence to compete when the right property appears and the discipline to walk away when the terms do not protect your interests.
Social Cookies
Social Cookies are used to enable you to share pages and content you find interesting throughout the website through third-party social networking or other websites (including, potentially for advertising purposes related to social networking).