A home can look right at the showing, fit the budget on paper, and still raise two very different questions once you are under contract: Is this property in sound condition? And is it worth the price being financed? That is where home inspection versus appraisal becomes critical. Buyers often treat these as interchangeable steps because they happen around the same time. They are not. Each has a different purpose, a different professional behind it, and a different effect on your transaction.
For buyers in Pennsylvania and New Jersey, knowing the difference helps you make decisions based on facts instead of assumptions. For sellers, it helps prevent surprises and keeps negotiations grounded in what the report actually says.
Home Inspection Versus Appraisal: Different Jobs
A home inspection evaluates the home’s visible condition and major systems. An appraisal estimates the property’s market value for the lender. One is primarily about the physical house. The other is primarily about the collateral supporting the loan.
Neither replaces the other. A property can appraise at or above the contract price and still have an aging roof, an unsafe electrical panel, drainage issues, or a failing HVAC system. Just as easily, a well-maintained home can receive an appraisal below the agreed purchase price if comparable recent sales do not support that number.
The practical difference is simple: the inspection is a buyer’s due-diligence tool, while the appraisal is generally a lender requirement. Both can affect negotiations, but they do so for different reasons.
What a Home Inspection Tells You
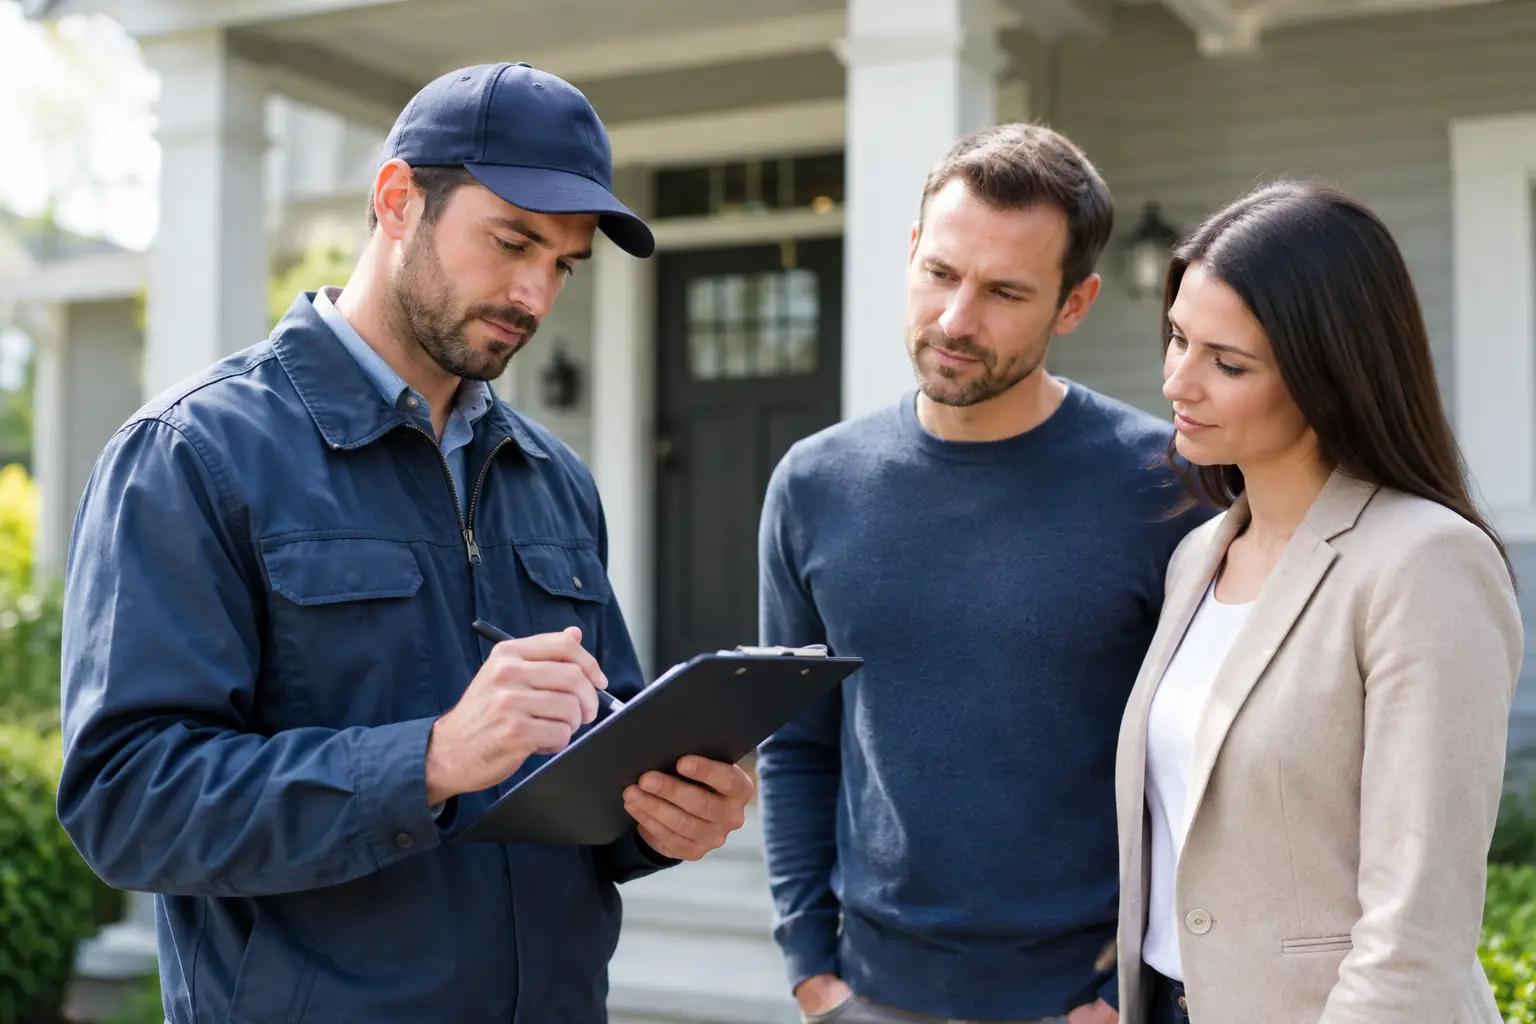
The buyer usually hires and pays for the home inspector. The inspector works for the buyer, not the lender, seller, or real estate agent. A standard inspection is a visual, noninvasive review of accessible components, including the roof, foundation, structure, plumbing, electrical system, heating and cooling, windows, appliances, and visible signs of moisture or damage.
An inspection report is not a pass-or-fail grade. Nearly every home, including new construction, has findings. The question is whether those findings point to safety concerns, major upcoming costs, active damage, or conditions that change your willingness to move forward at the current terms.
A good report separates routine maintenance from problems that deserve immediate attention. A loose handrail, missing GFCI outlet, or aging water heater may be manageable. Active knob-and-tube wiring, a compromised sewer line, widespread mold-like growth, structural movement, or a roof near the end of its service life requires a more careful discussion.
In older housing stock across the Philadelphia region, buyers should expect inspection findings. Homes in Bucks, Montgomery, Chester, Burlington, and Mercer counties may have original systems, stone foundations, older sewer laterals, oil tanks, septic systems, or additions completed under different building standards. Age alone is not a reason to walk away. Deferred maintenance, unclear repairs, and costly risks are where the decision gets more serious.
The inspection contingency in your contract gives you a defined period to review the findings. Depending on the agreement, you may request repairs, seek a credit, renegotiate the price, accept the property as-is, or terminate within the contingency terms. The right approach depends on the issue, the market, and your plans for the home.
What an inspection does not do
A standard inspection does not guarantee future performance or uncover every hidden defect. Inspectors cannot see behind finished walls, under flooring, or inside inaccessible areas. They also may recommend further evaluation by a licensed specialist for conditions involving foundations, chimneys, sewer lines, roofs, electrical systems, or environmental concerns.
When a report identifies a potentially expensive issue, get the right expert involved before negotiating. A general inspector may flag a concern, but a roofer, structural engineer, plumber, or electrician is better positioned to define the scope and cost of the repair. That extra step can prevent a negotiation based on a guess.
What an Appraisal Tells You
An appraisal is usually ordered by the lender after you apply for financing. The borrower typically pays the appraisal fee, but the appraiser must remain independent. Neither the buyer, seller, lender, nor agent can direct an appraiser to reach a particular value.
The appraiser considers the home’s location, size, condition, features, lot, and recent comparable sales. In many cases, the appraiser visits the property, documents its characteristics, and analyzes similar homes that sold nearby. The result is an opinion of market value as of a specific date.
For a buyer using a mortgage, the lender wants confirmation that the home supports the amount being borrowed. If you are buying for $500,000 with a loan, the lender does not want to base that loan on a home valued materially lower than the purchase price.
An appraisal is not as detailed as an inspection. Appraisers may recognize obvious condition issues that influence value or lender requirements, but they are not testing every outlet, inspecting the attic in the same manner, or estimating the remaining life of each system. Do not rely on an appraisal to tell you whether the house is mechanically sound.
What happens when the appraisal is low
If the appraisal comes in at or above the contract price, the transaction generally moves ahead, assuming other loan conditions are met. If it comes in low, there is a gap between the price you agreed to pay and the value the lender recognizes.
There are several possible paths. The seller may reduce the price. The buyer may bring additional cash to closing, if permitted and financially comfortable. The parties may meet in the middle. In limited situations, the buyer may challenge the appraisal with factual corrections or stronger comparable sales, although a successful reconsideration is never guaranteed.
Your appraisal contingency and financing terms matter here. Before offering above asking price or waiving protections, buyers should understand exactly how much cash they could contribute if the value does not support the contract price. A competitive offer should be intentional, not a blank check.
How Inspections and Appraisals Affect Negotiations
Inspection negotiations are usually condition-based. A buyer may ask for a credit toward a documented safety repair, a repair by a qualified contractor, or a price adjustment for a material defect. Sellers are not obligated to repair every item on the report, and buyers should avoid turning a serious review into a wish list for cosmetic updates.
Appraisal negotiations are value-based. The issue is not whether the seller maintained the home well. It is whether the available market evidence supports the agreed price for the lender. This distinction matters. A seller may reasonably decline a minor inspection request while still needing to address a low appraisal to keep the financed buyer in the deal.
The strongest negotiations focus on the actual problem and a practical solution. If the sewer scope reveals a damaged lateral, obtain an estimate. If an appraisal relies on a clearly inferior comparable sale, document the factual difference. Clear evidence creates a better conversation than frustration or pressure.
For VA buyers, the appraisal also has an added layer. A VA appraisal considers value and may identify property conditions that must be addressed to meet VA minimum property requirements. That does not make it a home inspection, and VA buyers should still complete a thorough inspection whenever possible. The appraisal protects the lender and the VA loan program. The inspection protects your understanding of the home you are buying.
Timing Matters More Than Most Buyers Realize
The inspection period often comes early in the contract timeline, while the appraisal is ordered after loan processing is underway. Delays can happen if the appraiser needs access, comparable sales are limited, or the lender requests additional documentation. In a fast-moving transaction, staying ahead of deadlines is part of protecting your options.
Buyers should schedule the inspection promptly after the contract is signed and review the report carefully with their agent. Sellers should provide reasonable access, maintain the property through closing, and be ready to discuss significant findings with a clear understanding of what the contract requires.
A disciplined process does not eliminate surprises. It does make them manageable. The goal is not to find a flawless house or force every issue onto the other party. The goal is to know what you are buying, understand what the lender will support, and make a decision that fits your finances and risk tolerance.
When an inspection finding or appraisal result changes the picture, slow down long enough to get the facts. The right home should be a decision you can stand behind well after closing day.
Social Cookies
Social Cookies are used to enable you to share pages and content you find interesting throughout the website through third-party social networking or other websites (including, potentially for advertising purposes related to social networking).