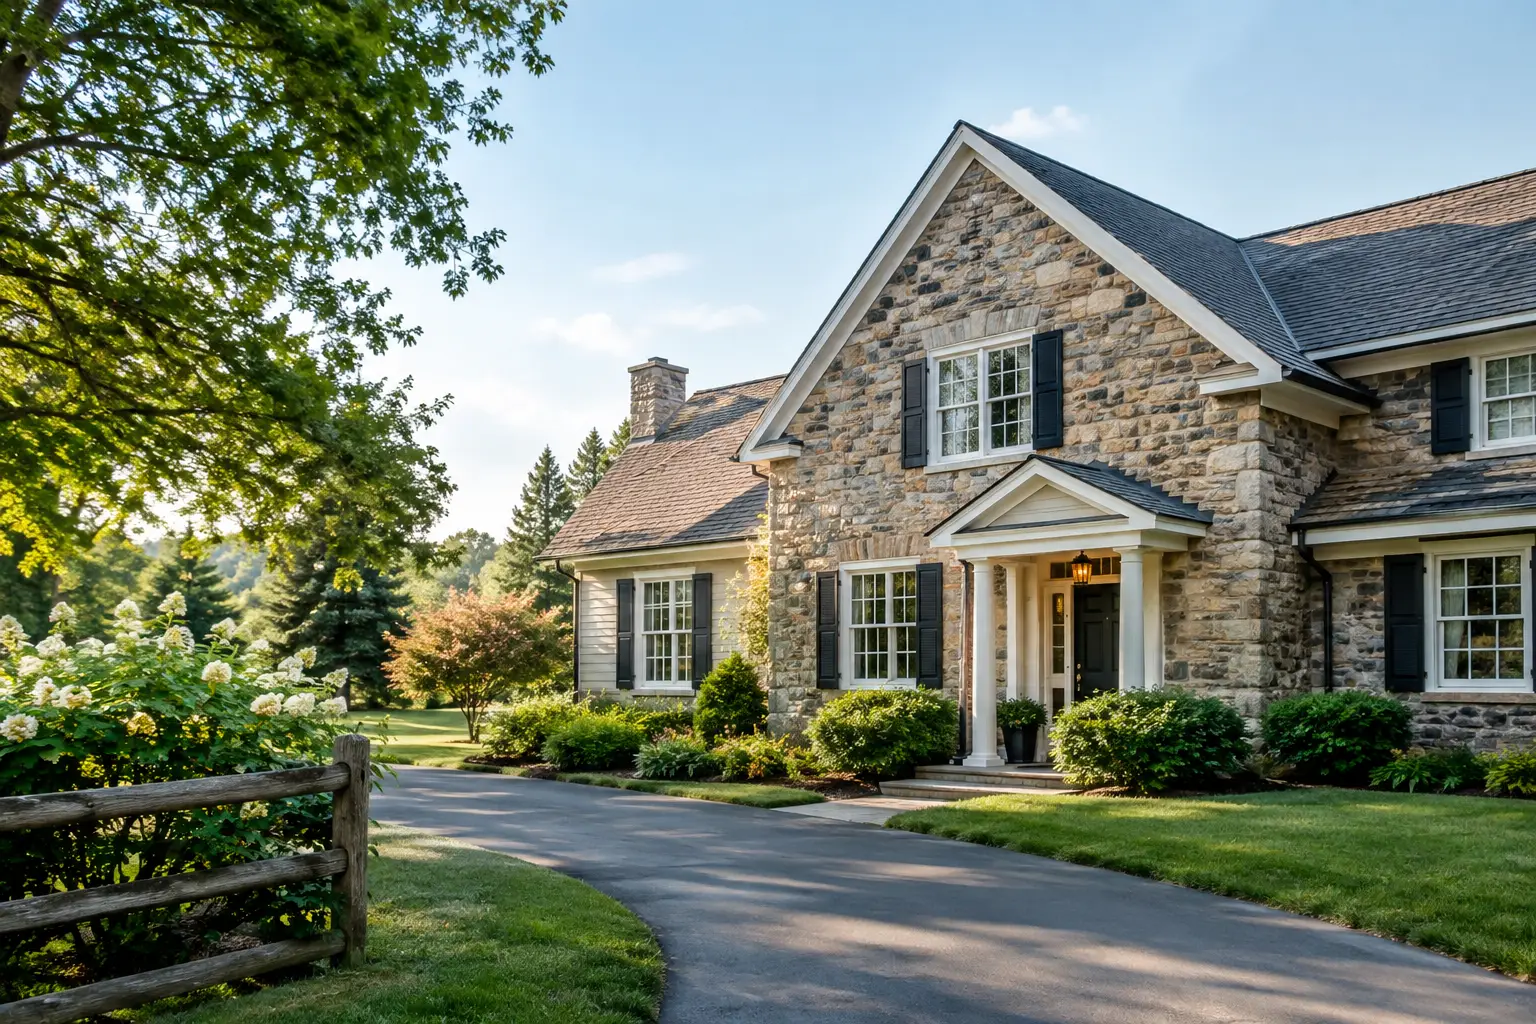
A home search in Bucks County can change quickly from one town to the next. A stone farmhouse outside Doylestown, a borough twin in Yardley, a newer townhome in Warrington, and a single-family home in Levittown may all fit the same broad budget, but they do not offer the same commute, tax picture, maintenance needs, or resale considerations. When reviewing Bucks County homes for sale, the right question is not simply, “Can I buy this house?” It is, “Does this property support the way I need to live and the financial position I want to protect?”
That distinction matters. A purchase is exciting, but it is also a contract, a financing decision, and a long-term commitment. Clear expectations at the beginning make it much easier to move decisively when the right property appears.
Start With the Town, Not Just the House
Bucks County offers a wide range of lifestyles within a relatively compact area. Buyers can choose established walkable boroughs, rural properties with acreage, commuter-friendly neighborhoods, river towns, and newer developments with homeowners associations. Each comes with benefits and trade-offs.
Newtown, Yardley, Doylestown, New Hope, Langhorne, Richboro, and Warminster are often searched by buyers who want access to restaurants, shopping, parks, rail options, or major commuter routes. Communities farther north or west may offer more land, privacy, and a different pace, though travel times and property upkeep can increase. Lower Bucks can make sense for buyers working in Philadelphia, New Jersey, or nearby employment centers, while Central Bucks often appeals to buyers seeking a particular school district or borough lifestyle.
Do not rely on a town name alone to make the decision. Two homes a few miles apart can fall into different school districts, municipalities, tax structures, flood zones, or utility arrangements. A property’s location affects daily life and monthly cost as much as its number of bedrooms.
Commute and routine deserve an honest look
Map the drive during the times you would actually use it. Check access to work, childcare, medical care, grocery stores, rail stations, and the people you see regularly. A house can look ideal during a Saturday showing and become less appealing after a week of inconvenient travel.
For military families and relocating buyers, this step is especially important. A move connected to a new assignment, separation from service, or a growing family often comes with a firm timeline. It helps to prioritize what must work on day one, then separate those needs from features that would simply be nice to have.
Build a Purchase Budget That Holds Up
The list price is only one part of what a home will cost. Before touring aggressively, buyers should understand a comfortable monthly payment, available cash for closing, expected reserves after closing, and the loan program that fits their situation.
Property taxes vary across Bucks County, sometimes significantly. Homeowners insurance, homeowners association fees, utilities, private well or septic maintenance, and needed repairs can also change the true cost of ownership. A lower-priced home with high taxes or extensive deferred maintenance may be less affordable than a higher-priced home in better condition.
A lender preapproval is more useful than a quick online estimate because it reviews income, assets, debts, and loan eligibility. It also helps determine whether a conventional, FHA, jumbo, or VA loan is appropriate. Veterans and active-duty buyers should not assume a VA loan puts them at a disadvantage. With solid preparation, accurate documentation, and a lender who understands the program, VA financing can be a strong option. The property still needs to support the appraisal and loan requirements, so timing and communication matter.
Keep a realistic reserve after closing. Buying every dollar of home a lender says you can qualify for may leave little room for a roof repair, a moving expense, or the basic updates that make a house feel like yours. The right budget is the one that lets you own confidently, not just get to the closing table.
How to Evaluate Bucks County Homes for Sale
Online photos are useful for narrowing options, but they do not reveal everything that affects value. During a showing, look beyond finishes and staging. Pay attention to the age and apparent condition of the roof, windows, heating and cooling systems, electrical panel, drainage, driveway, basement, and exterior grading.
Older Bucks County homes can offer character, mature neighborhoods, and strong locations. They may also need more careful review. Original details are not automatically problems, but older plumbing, outdated electrical systems, aging mechanicals, and moisture intrusion can become expensive if ignored. A renovated kitchen does not erase concerns in the systems behind the walls.
Newer construction brings its own considerations. Buyers should review homeowners association rules, monthly or quarterly fees, resale restrictions, builder warranties, and the likelihood of future development nearby. A low-maintenance townhome can be an excellent fit, but the association’s financial health and rules deserve the same attention as the unit itself.
Watch for location-specific factors
Some properties require additional due diligence because of their setting. Homes near waterways may warrant flood insurance research. Rural properties may have a well, septic system, propane, oil heat, or a long private drive. Historic or protected areas may have restrictions that affect renovations. None of these factors automatically means “walk away.” They mean ask better questions before writing an offer.
A thorough inspection is a key part of that process, but it is not a substitute for thoughtful selection. Inspections identify conditions at a point in time. Buyers still need to decide which findings are manageable, which require negotiation, and which create more risk than the property is worth.
A Strong Offer Is More Than the Highest Number
In a competitive situation, price matters, but it is not the only term a seller evaluates. Financing strength, earnest money, requested contingencies, inspection approach, settlement timing, and the likelihood of a clean closing all influence an offer’s appeal.
That does not mean buyers should waive protections casually. An offer that looks aggressive but exposes you to avoidable risk is not a victory. The best strategy depends on the home, competing activity, your financing, and your comfort level with repairs and appraisal exposure. Some buyers need a home-sale contingency or a full inspection contingency. Others can be more flexible. The right approach is specific to the transaction, not copied from a headline or a neighbor’s experience.
Before submitting, review the comparable sales, not just the asking price. A well-priced property may attract immediate interest, while another may have been on the market longer because its condition, location, or pricing needs to be addressed. A disciplined market analysis helps you make an offer you can defend emotionally and financially.
Inspection, Appraisal, and Closing: Stay Engaged
Once an offer is accepted, the work is not over. The inspection period, mortgage application, appraisal, title work, and final walkthrough all require attention. Missed deadlines can weaken your position or delay the transaction.
During inspections, focus on material issues: structural concerns, water problems, safety items, major systems, and repairs that affect the home’s usability or cost. Expect that nearly every property will have findings. The goal is not to find a perfect house. It is to understand what you are buying and negotiate reasonably when the facts support it.
If an appraisal comes in below the contract price, there may be several paths forward. The buyer and seller might renegotiate, the buyer might bring additional funds if appropriate, or the parties may challenge factual errors with supporting information. There is no automatic answer. Good representation means explaining the options plainly, protecting your contingencies, and avoiding pressure to make a decision you do not understand.
Clear communication also matters with your lender, inspector, title company, and insurance provider. Delays often begin with an unanswered request or an assumption that someone else is handling a detail. A steady, organized process reduces last-minute surprises.
Make the Decision You Can Stand Behind
The best home is not always the largest, newest, or most photographed. It is the one that meets your core needs, fits your financial plan, and remains a sound decision after the emotion of the showing wears off. That may mean choosing a smaller home in a location you value, accepting cosmetic updates for better long-term value, or walking away when inspection results reveal more risk than you want to carry.
Alexander Shulzhenko approaches that decision with direct guidance, local perspective, and a commitment to protecting the client’s interests from the first showing through closing. A good real estate decision should feel informed, not rushed.
When you find a Bucks County property that deserves serious consideration, slow down long enough to verify the details. The right home is worth pursuing with confidence, discipline, and a plan that still makes sense after you receive the keys.
Social Cookies
Social Cookies are used to enable you to share pages and content you find interesting throughout the website through third-party social networking or other websites (including, potentially for advertising purposes related to social networking).